Invest in Oil and Gas with Your Self-Directed IRA
Many of our investors use Advanta IRA to hold their self-directed retirement accounts for oil and gas investments.
Relationship disclosure. Advanta IRA is an independent third-party custodian and is not part of Kingdom Exploration. Advanta IRA does not provide investment advice and does not endorse, evaluate, or recommend any investment, including ours. Kingdom Exploration does not provide custodial, tax, or legal services. You are free to use any qualified self-directed custodian willing to hold an oil and gas working interest; we mention Advanta IRA because investors have used them. Any referral, marketing, or compensation arrangement between Kingdom Exploration and a custodian is disclosed in the offering documents provided to prospective investors — ask for it directly if it matters to your decision.
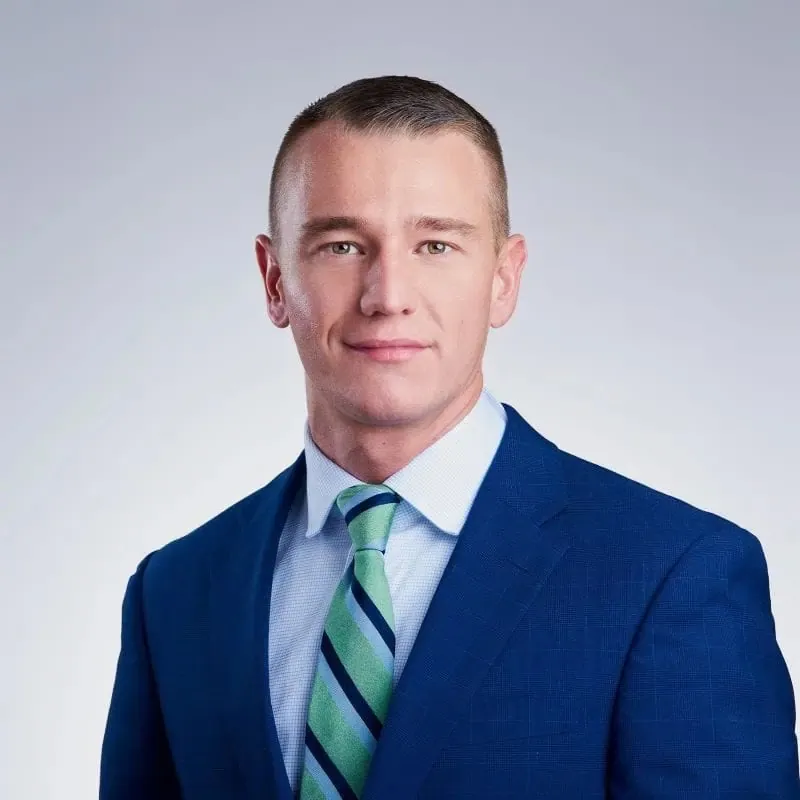
Meet Owen Lynn
Senior Educator and Business Development Executive, Advanta IRA
Owen brings over 11 years in financial services (TD Ameritrade, Merrill Lynch) and 6 years specializing in self-directed IRAs. He has worked with thousands of investors - from first-time alternative investors to experienced fund managers.
"We enjoy helping individuals use their retirement funds to invest in oil and gas and look forward to helping you with your investment journey."
Direct: 727.221.0095
About Advanta IRA
Advanta IRA reports managing over $3.7 billion in client assets with an A+ BBB rating and 20+ years of experience. (Figures as published by Advanta IRA; we have not independently verified them.) Many Kingdom Exploration investors have chosen Advanta IRA as their custodian for self-directed retirement accounts.
What is a Self-Directed IRA?
A Self-Directed IRA (SDIRA) gives you complete control over your investment decisions beyond stocks and bonds. With an SDIRA, you can invest in:
Oil and Gas
Real Estate
Precious Metals
Cryptocurrency
Private Placements
Private Lending
Account Types Supported by Advanta IRA
Advanta IRA supports multiple retirement account types that can be self-directed into oil and gas investments. Each has different contribution limits, tax advantages, and eligibility requirements:
How It Works
Contributions are made with pre-tax dollars and may be tax-deductible. Earnings grow tax-deferred until withdrawal. Best if you expect a lower tax bracket in retirement.
2026 Limits
- Annual Contribution: $7,500
- Catch-Up (50+): $1,100 additional ($8,600 total)
- Rollover: Unlimited from 401(k)
Source: IRS Notice 2025-67. Limits are adjusted annually — confirm current figures at IRS.gov.
How It Works
Contributions made with after-tax dollars. Qualified distributions of earnings in retirement are tax-free. Contributions can be withdrawn anytime tax-free.
2026 Limits
- Annual Contribution: $7,500
- Catch-Up (50+): $1,100 additional ($8,600 total)
- Income Limit: Phase-out $153,000–$168,000 (single) / $242,000–$252,000 (married filing jointly)
Source: IRS Notice 2025-67. Limits are adjusted annually — confirm current figures at IRS.gov.
How It Works
Simplified Employee Pension for self-employed individuals and small business owners. Only employers contribute (not employees). Lower administrative costs and flexible annual contributions.
2026 Limits
- Annual Contribution: Up to $72,000
- Or: 25% of compensation (whichever is less)
- Compensation cap: $360,000 considered
- No Catch-Up: Same limit regardless of age
Source: IRS 2026 COLA limits. Confirm current figures at IRS.gov.
How It Works
Savings Incentive Match Plan for Employees - designed for small businesses with fewer than 100 employees. Requires employer matching (up to 3%) or non-elective contributions (2%).
2026 Limits
- Employee Contribution: $17,000 ($18,100 for certain applicable plans)
- Catch-Up (50+): $4,000 additional
- Ages 60–63: $5,250 catch-up
- Plus: Employer match or contribution
Source: IRS Notice 2025-67. Confirm current figures at IRS.gov.
How It Works
For self-employed individuals or business owners with no full-time employees (except spouse). Allows both employee and employer contributions. Can include Roth option with no income limits.
2026 Limits
- Employee Deferral: $24,500
- Total Additions: Up to $72,000
- Catch-Up (50+): $8,000 additional
- Ages 60–63: $11,250 catch-up
- Loan Option: Up to 50% of vested balance, subject to plan terms and statutory caps
Source: IRS Notice 2025-67 and 2026 COLA limits. Confirm current figures at IRS.gov.
How It Works
Traditional employer-sponsored 401(k) plans typically do not allow self-direction into alternatives while employed. However, funds from former employer 401(k)s can be rolled over to a Self-Directed IRA.
2026 Limits
- Employee Contribution: $24,500
- Catch-Up (50+): $8,000 additional ($32,500 total)
- Ages 60–63: $11,250 catch-up ($35,750 total)
- Rollover: Unlimited to SDIRA
Source: IRS Notice 2025-67. Confirm current figures at IRS.gov.
How It Works
Triple tax advantage: tax-deductible contributions, tax-free growth, and tax-free withdrawals for qualified medical expenses. After age 65, can be used for any purpose (taxed as income, no penalty).
2026 Limits
- Self-Only: $4,400
- Family: $8,750
- Catch-Up (55+): Additional $1,000
- Requires: High-deductible health plan
Source: IRS Rev. Proc. 2025-19. Confirm current figures at IRS.gov.
Watch: Sean Pruitt and Owen Lynn Discuss IRA Oil Investment
Learn directly from our experts about the full investment process, tax benefits, and get your questions answered.
The Underlying Tax Benefits (and Who Actually Gets Them)
The 2025 tax legislation (H.R. 1, the "One Big Beautiful Bill Act") preserved the framework below rather than creating a deadline. Read this section with one thing in mind: when you invest through a retirement account, these benefits accrue to the account, not to you personally. The deductions in the first two cards are the main reason many investors choose to invest outside a retirement account instead.
100% Bonus Depreciation
100% bonus depreciation was restored on a permanent basis for qualifying property. It applies only once equipment is placed in service — equipment not in service by December 31 produces no deduction that year.
Intangible Drilling Costs
First-year expensing under IRC §263(c) remains intact with no scheduled sunset. IDCs commonly represent 60–85% of well costs; the deduction can be deferred by the §461(l) excess business loss and §465 at-risk rules.
15% Percentage Depletion
A deduction equal to 15% of gross income from the property — not tax-free income. Capped at 100% of taxable income from the property and 65% of overall taxable income, limited by the small-producer exemption (roughly 1,000 bbl/day), and subject to §1254 recapture on sale.
Active (Non-Passive) Treatment
Under IRC §469(c)(3), a working interest is non-passive only where it is held in a form that does not limit your liability (for example, a general partner interest or direct working interest). Where that holds, losses can offset W-2 and other active income.
Understanding UBTI for Oil and Gas IRAs
This is the single most important section on this page, and the one most often glossed over. A retirement account is normally tax-exempt, but that exemption does not extend to income from operating a business — and producing oil and gas through a working interest is operating a business. That income is generally Unrelated Business Taxable Income (UBTI), taxable to the account itself each year.
What Triggers UBTI
- Working interest income from oil and gas operations
- Active trade or business income through pass-through entities
- Debt-financed investment income (UDFI)
By contrast, royalty income is generally excluded from UBTI. The distinction between a working interest and a royalty interest matters a great deal here.
Filing Requirements
- Form 990-T is required if gross UBTI is $1,000 or more for the year
- The tax is paid from IRA funds, not by you personally — the account must hold cash to pay it
- The custodian may or may not prepare the return; confirm who does, and what it costs
- Due April 15 (extension available)
Trust rates are compressed — "10–37%" is misleading shorthand
UBTI is taxed at the rate schedule for estates and trusts, not the individual schedule. Seeing "10–37%" suggests there is room at the bottom. There is almost none. For 2026 the schedule runs:
| Taxable income (estates & trusts, 2026) | Rate |
|---|---|
| Not over $3,300 | 10% |
| $3,300 – $11,700 | 24% |
| $11,700 – $16,000 | 35% |
| Over $16,000 | 37% |
Source: IRS Rev. Proc. 2025-32, Table 5. Thresholds are adjusted annually. The practical point: an individual does not reach 37% until roughly $640,600 of taxable income in 2026, but a trust or IRA reaches it at $16,000. Any meaningful production income inside the account is likely taxed at or near the top rate.
What reduces UBTI (the part usually left out)
UBTI is a net figure, not gross revenue, and the same oil and gas deductions that make direct investment attractive generally apply inside the account when computing it:
- Percentage depletion and intangible drilling costs are deductions connected with the same activity and generally reduce the account's UBTI. In the early years, IDC deductions can offset a substantial portion of the account's unrelated business income.
- Operating expenses directly connected with the activity — lease operating expense, severance taxes, and similar costs — also reduce it.
- A $1,000 specific deduction is available in computing the tax.
- Losses may generally be carried forward, though the rules require unrelated trades or businesses to be computed separately.
The honest summary: UBTI is a real cost that erodes the tax-shelter advantage of holding a working interest in a retirement account, but it applies to net income after these deductions, not to gross checks. Have your CPA model it before you commit — do not rely on either the scary version or the rosy version.
Prohibited Transactions and Liquidity: The Risk Specific to IRAs
This risk is unique to retirement accounts and carries the largest consequence on the page, so it is worth being blunt about.
The IRA must pay every expense of the investment from its own funds. That includes capital calls, its share of operating costs, the 990-T tax, custodian fees, and eventual plugging and abandonment (P&A) costs at the end of the well's life.
If you pay any of those personally, you have likely engaged in a prohibited transaction under IRC §4975. The consequence is not a small penalty: a prohibited transaction can disqualify the entire IRA, treating the whole account as distributed and taxable in that year — potentially with penalties, and on a balance far larger than the oil investment itself. Writing a personal check to cover an unexpected $8,000 cash call, to save an investment you believe in, is exactly how this happens.
Therefore: keep meaningful cash reserves inside the account. Do not invest the account down to a near-zero cash balance. Discuss a reserve amount with your custodian and CPA before funding, and ask the operator what future capital calls and P&A obligations are realistically expected. Related rules also bar the account from transacting with disqualified persons (you, your spouse, ancestors, descendants and their spouses, and entities they control) and from any personal benefit or use of the asset.
Retirement accounts are also subject to required minimum distributions on traditional accounts, and an illiquid working interest can be difficult to value or distribute when an RMD comes due. Valuation of the interest for annual custodial reporting is your responsibility, not the custodian's. These are administrative realities worth understanding before you fund.
Direct Investment vs. IRA Investment
| Feature | Direct Investment | Self-Directed IRA |
|---|---|---|
| IDC Deduction | Deductible on your personal return where you hold the interest in a form that does not limit your liability, subject to §461(l) and at-risk limits | Stays within the account — no personal deduction |
| Production Income | Taxable to you annually; percentage depletion available subject to limits | Tax-deferred or tax-free to you, net of UBTI |
| Annual Tax Inside the Account | N/A | UBTI at trust rates (37% over $16,000 in 2026), paid from account funds |
| Self-Employment Tax | Generally applies to a general partner's distributive share | Not applicable to the account |
| Liquidity Requirement | You fund cash calls personally | Account must hold cash for calls, P&A, and 990-T tax — paying personally risks disqualification |
| Best For | Investors seeking a current-year deduction against active income | Investors with retirement capital and no need for a personal deduction |
How to Get Started
Contact Kingdom Exploration
Discuss opportunities and verify you qualify as an accredited investor.
Schedule SDIRA Consultation
Book a free call with Owen Lynn at Advanta IRA.
Open Your Account
Advanta handles paperwork (1-2 business days).
Fund via Transfer/Rollover
Move funds from existing IRA or 401(k) (5-10 days).
Review and Execute
Sign documents, and Advanta processes the investment.
Receive Updates and Any Distributions
Project updates from the operator. Any distributions are deposited into the IRA, never to you personally. Amounts and timing depend on production, prices, and costs, and are not guaranteed.
Frequently Asked Questions
Ready to Get Started?
Contact Kingdom Exploration first to discuss opportunities, then schedule your free SDIRA consultation with Owen Lynn.
Advanta IRA Disclaimer: Advanta IRA and its employees do not provide investment advice or endorse any products. All information is for educational purposes only. Consult your attorneys, accountants, and financial advisors before investing.
Kingdom Exploration Disclaimer: Sean Pruitt is not a CPA, tax attorney, or financial advisor. Nothing here should be taken as tax, legal, or investment advice. Consult qualified professionals before investing.
Risk Disclosure: Oil and gas investments carry significant risk, including potential loss of your entire investment. Past performance does not guarantee future results.

